
The Startup Founder's Guide to Revenue-based Financing [2026]

2 mins
Most growing SaaS companies eventually hit the same fork in the road. Raise another equity round and watch the cap table get thinner, or run growth experiments on whatever the bank balance allows. Revenue-based financing (RBF) is the third path more founders are taking.
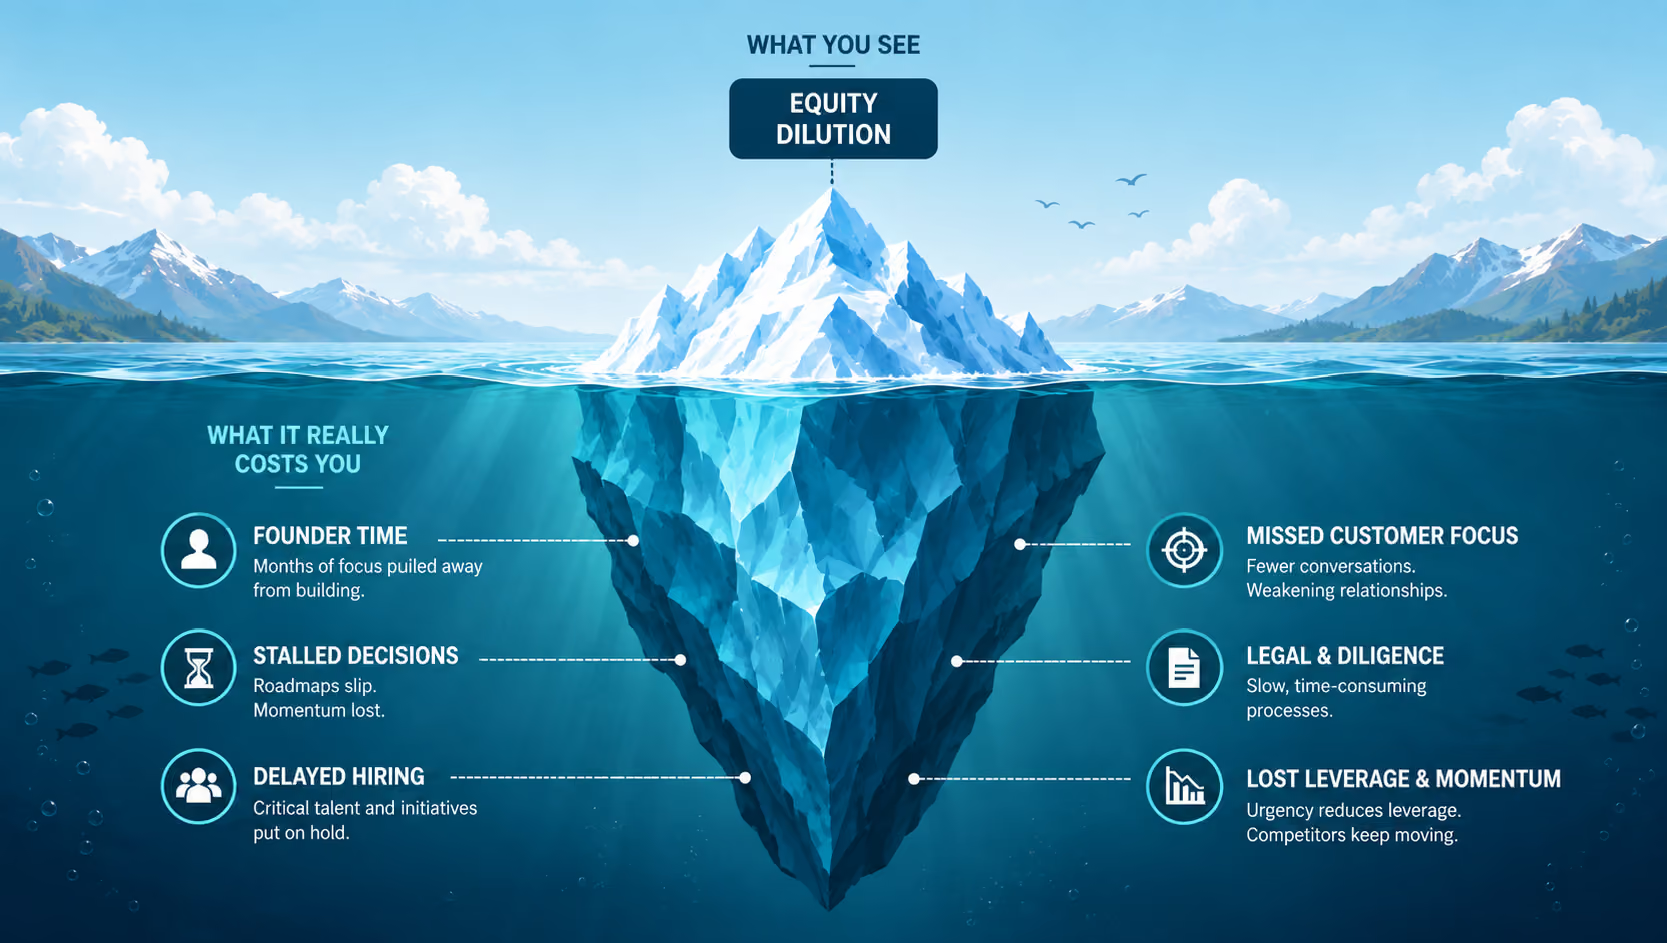
It’s no longer a niche option either. Founders are increasingly weighing it against the real cost of the status quo. According to Carta’s State of Private Markets Q1 2026 report, median dilution for startups on Carta was about 19% at seed and 18% at Series A. Stack those two rounds together, and a founder’s ownership stake is down by roughly a third, before they’ve even hit Series B.
So that’s the backdrop. This guide walks through how revenue-based financing works, what it costs down to the dollar, who gets approved, and when it’s genuinely the right call instead of just the trendy one. Bookmark it, because future-you, staring down a runway spreadsheet at 1 a.m., is going to want it.
What is revenue-based financing?
Revenue-based financing is a type of financing where a company borrows money upfront in exchange for a percentage of its future revenue, repaid through smaller recurring payments until the full amount is settled.
Conceptually, it behaves like debt: dollars borrowed upfront, smaller payments over time, until the loan’s fully repaid. The difference is in how those smaller payments are structured. Instead of a predetermined fixed-interest payment, they’re usually a percentage of revenue, so the payment moves with however your month actually went.
Some people call it recurring revenue financing instead, since the whole arrangement is underwritten against recurring revenue rather than collateral or years of credit history. Different label, same mechanism.
This financing model has roots in the US and European markets, but it’s increasingly resonating in regions like India, Singapore, and Latin America too.
And RBF isn’t flying solo here. It’s one form of non-dilutive capital, a bigger category that also covers venture debt, grants, and ARR-based funding. All of them fund growth without issuing new shares, but they part ways on cost, repayment structure, and who qualifies. Think of non-dilutive capital as the whole menu, and RBF as the dish most people end up ordering.
What are the types of revenue-based financing?
Revenue-based financing comes in two types: variable revenue-linked payments and fixed-term payments. The first repays a fixed percentage of revenue each month, so payments rise and fall with sales; the second repays a predetermined amount each month over an agreed term, regardless of how revenue moves.
Here’s how each one plays out side by side.
How is revenue-based financing repaid, and what does it cost over a 12-month term?
On a 12-month fixed-fee structure, you repay the capital plus a flat fee in equal monthly installments; for example, $500,000 at a 10% flat fee costs $50,000 in total, repaid as $550,000 across 12 months, or about $45,833 a month.
The appeal here is that you know the full cost before you ever sign anything, no surprises buried in a term sheet.
Here’s the formula, in case you want to run your own numbers.
Monthly payment = (Funding amount + (Funding amount × Fee %)) ÷ Term in months
And here’s what that looks like applied to three common funding amounts, at both a 10% and a 12% fee over 12 months.
On a variable model, the total repayment is capped instead; say, a 1.2x cap on $100,000 tops out at $120,000, but the monthly payment and the length of the term move with however your revenue behaves.
A revenue-based financing example with LemonadeStand

Let’s say you’re running LemonadeStand, a software company that crossed $1M in annual recurring revenue in year one, funded by savings, a co-founder, and whichever relatives believed in you enough to write a check. Classic founder starter pack.
Year two is where it gets interesting. Growth needs cash, and you’d still like to own your company when this is all over. With RBF, you take $100,000 today at a 10% fixed fee over 12 months. Work the math, and that’s $110,000 divided by 12, or about $9,167 a month, so $10,000 in total fees for the year. Not one share of LemonadeStand changes hands.
The whole point is to put that money to work fast enough that monthly revenue climbs faster than the monthly repayment: scale a business before the repayment clock catches up with you. When life hands you ARR, you make runway, not lemonade.
How do debt, equity, and interest rates shape your cost of capital?
Debt is generally the cheapest capital because lenders are repaid first and their upside is capped, while equity is the most expensive because investors are repaid last and expect to share in the full upside, with interest rates on risk-free government debt setting the floor for both.
Every financing decision really comes down to one blunt question: What does this money cost you? Consider it the eat-your-vegetables section, a little dry, but it makes everything after this easier to digest.
Equity
Equity is ownership, plain and simple. Equity investors get repaid last if things go sideways, so they’re taking the biggest risk, and they expect the biggest upside in return. That’s why equity tends to suit early-stage startups that could realistically grow 100x, and also why raising it dilutes everyone who already owns a piece. Selling equity early is a bit like selling a slice of a pizza that might, someday, be the size of a stadium.
Debt
Debt, on the other hand, is money you borrow and repay. Lenders get repaid first, and their upside is capped, so debt tends to be cheaper, just harder for an early-stage company to get its hands on.
Interest rate
Interest rates set the floor underneath both. In the US, the Federal Reserve sets a target range for the federal funds rate, and Treasury yields roughly track where markets expect that rate to land. Because Treasuries are treated as risk-free, no investor is going to lend to a riskier startup for less than that.
For debt specifically, three factors push the price above that baseline.
- Ability to repay: Reliable cash flow lowers the risk and the rate.
- Security: Pledged assets such as receivables give the lender something to recover, which lowers the rate.
- Seniority: Lenders repaid first in a bankruptcy charge less. Bank debt is typically senior, while venture debt sits lower and costs more.
Revenue-based financing sits somewhere between the two: non-dilutive like debt, but underwritten against recurring revenue rather than collateral or a decade of credit history.
How does revenue-based financing work?
Revenue-based financing works by advancing capital against your future revenue, which you then repay in monthly installments until you hit an agreed cap or term, with no collateral or equity typically required.
The breakdown below covers each stage in more detail:
- The agreement: You get an upfront advance against future revenue; no equity changes hands. How it’s classified (a purchase of receivables, a fixed-fee facility, whatever the provider calls it) varies, so read the fine print closely.
- Repayment: Payments usually kick in the following month, either as a set amount or a percentage of revenue you agreed to upfront. No plot twists.
- The cap: Repayments stop once you hit the agreed total or reach the end of the term, depending on the provider.
- Additional funding: Plenty of companies draw again, sometimes in tranches, portions of an approved facility that each get repaid on their own schedule.
- Collateral: RBF usually skips physical assets entirely, though a few providers do take a security interest in receivables, so check the terms either way.
Who qualifies for revenue-based financing?
Most revenue-based financing providers require recurring revenue and a short revenue history, and at Efficient Capital Labs (ECL), the typical minimum is $500K in annual recurring revenue (ARR), at least 3 months of runway, and at least 6 months of revenue history.
Underneath all the paperwork, it usually comes down to one blunt test: can a lender actually underwrite your recurring revenue, not just your balance sheet. Thresholds do vary by provider, so it’s worth shopping around if you’re right on the edge of qualifying.
Three questions tend to come up once founders get this far:
1. How much ARR do I need to qualify for revenue-based financing?
Minimums vary widely across the market, so there’s no single number that applies everywhere. For ECL specifically, that minimum unlocks funding of $100K to $5M, sized at up to roughly 60% of ARR, and ECL’s decisioning engine, AURA, evaluates each business individually rather than applying a hard cutoff.
2. Do I need 12+ months of revenue history to qualify for revenue-based financing?
Not necessarily. Plenty of providers will work with a shorter window if the revenue is recurring and predictable. Beyond raw length, what gets scrutinized is revenue quality: retention, renewals, contracted billing, and how concentrated revenue is across customers. No decade of audited financials or a framed bank statement on the wall required.
3. What do revenue-based financing providers look at?
Revenue-based financing providers evaluate your business model, revenue scale, revenue history, runway, legal entity, and financial data, with the predictability of your recurring revenue carrying the most weight of all.
Here’s how each of those criteria breaks down against ECL’s typical requirement:
What can revenue-based financing be used for?
Revenue-based financing works best for startups bridging to a funding round, SaaS and AI companies with recurring or usage-based revenue, and ecommerce, service, and gaming businesses with predictable or seasonal revenue cycles.
Here’s where it tends to work best, in a bit more detail.
1. Startups bridging to the next round
Startups usually have little to no credit history, which makes bank loans a tough ask, so RBF providers look at a short window of revenue instead and work with that.
2. SaaS and AI companies
The predictable revenue streams of SaaS companies align well with the RBF model, which is exactly why it’s become such a popular choice in this sector. Steady subscriptions make the underwriting easy, and revenue-linked repayments smooth out the gap between subscription inflows and fixed costs like payroll. Payroll, famously, does not wait around for annual contracts to pay out.
AI companies get an extra reason to pay attention here. Inference and GPU costs scale with usage, so burn can climb even while growth looks genuinely healthy, and revenue-linked capital can fund that compute without pricing an entire equity round around what might just be a temporary cost spike.
3. Ecommerce, service firms, and gaming studiosf
Subscription ecommerce brands, agencies, and IT outsourcing firms tend to have steady recurring revenue too, so the same logic applies. Gaming studios are a slightly different case: they spend heavily before a release and earn heavily after it, so RBF can pull that post-launch revenue forward to fund development in the meantime. About the closest thing to a time machine most finance teams are ever going to get.
Read more on the best uses for RBF here; there are a few more niche fits worth knowing about.
How does revenue-based financing compare with venture capital, venture debt, and bank loans?
Revenue-based financing is non-dilutive and typically faster to access than venture capital, venture debt, or bank loans, but it requires existing recurring revenue and usually offers smaller amounts than a large equity round.
Here’s how all four stack up side by side:
Most founders use several of these over time, matching each to the job it does best.
Why founders choose revenue-based financing
Founders tend to pick revenue-based financing for three fairly practical reasons, all tied to ownership, cost, and control.
- No equity dilution: Equity rounds commonly trade 15 to 25% of the company, and venture debt can include warrants. RBF leaves your cap table exactly as it is.
- Predictable cost: On a fixed-fee structure, the cost is set upfront and doesn’t compound.
- Control: No board seats, no outside votes, and no growth targets set by someone else.
The trade-offs of revenue-based financing
Revenue-based financing isn’t without trade-offs, and they’re worth weighing honestly before you sign anything.
- Smaller amounts: RBF is sized as a share of ARR, so it usually won’t match a large equity round.
- Revenue required: Providers want recurring revenue, ideally subscriptions or contracts, which happens to be good news for SaaS founders, since that’s basically their whole business model.
- Repayments start right away, so the money really needs to go into things that earn revenue or protect runway within the term: Great fuel for a growth engine, a genuinely bad fit for a moonshot.
How do the alternatives to revenue-based financing stack up?
Each alternative trades a different thing for capital, whether that’s equity, flexibility, or collateral, so most founders end up combining revenue-based financing with one of these rather than relying on just one.
- Venture debt offers longer terms for venture-backed startups, but it can come with warrants and pledged assets attached. For a deeper comparison, see venture debt vs non-dilutive capital.
- Venture capital funds big, ambitious bets early and brings a network along with it, but it costs equity, and usually a board seat too. Fresh VC money is tighter than it used to be as well: US VC firms raised $66.1 billion in 2025, according to the PitchBook-NVCA Venture Monitor. If you keep raising every time you need cash, you might eventually look at the cap table and wonder whose company this actually is anymore.
- Bank loans are usually the cheapest capital around, but banks want strong credit histories, and fixed payment dates can clash awkwardly with SaaS cash that tends to arrive in clumps around renewals.
- Bootstrapping keeps 100% of the upside, but it leaves you with very little buffer if the market turns, which is exactly why it pairs so well with non-dilutive capital. TechGenies, a bootstrapped software firm operating across ten countries, used ECL financing to hire a Head of Sales and a Head of Marketing Strategy while keeping 100% of its equity.
How does Efficient Capital Labs (ECL) approach non-dilutive capital?
Efficient Capital Labs (ECL) is a non-dilutive capital provider for B2B SaaS and AI companies with recurring revenue, advancing $100K to $5M, up to roughly 60% of ARR, with no equity, warrants, or board seats taken.
It operates across the US, India, and Singapore, and here’s what sets its approach apart:
- Built for SaaS and AI companies: ECL funds venture-backed and bootstrapped companies, many operating from India or Singapore and selling into the US.
- Decisions by AURA, with human judgment: AURA (Agentic Underwriting & Risk Analytics) reviews banking data, financial statements, contracts, and counterparty information and turns them into a decision with a visible reason behind it. It delivers 95% of decisions within 72 hours, with a team of former founders and operators reviewing each one.
- ECL’s own capital: ECL funds every deal from its own balance sheet, financed in part through its own debt facility, and carries the risk directly, which gives founders certainty of funds. All funding is disbursed in USD, including into eligible multi-currency accounts.
- Disclosed terms: Pricing is typically ~10 to 12% annualized in USD, with monthly payments that include both principal and interest. The exact rate depends on factors like revenue stability, growth, and risk profile, but the full terms are disclosed upfront before you accept an offer, with no warrants, board seats, or personal guarantees.
Is revenue-based financing right for your company?
Revenue-based financing is usually a strong fit if you have predictable recurring revenue, a specific use for the capital that will pay back within the repayment term, and ownership is a genuine priority, and it’s usually a poor fit if you’re pre-revenue, your revenue is highly concentrated or volatile, or you need capital for a multi-year bet with no near-term return.
Before deciding either way, ask yourself whether revenue can support the monthly repayments, what return the funded project is supposed to deliver, and how the total RBF cost stacks up against the dilution cost of raising that same amount in equity instead. Then pressure-test your own answer with a quick financial model and a conversation with founders who’ve used RBF before. Ten minutes with a spreadsheet now beats ten weeks of second-guessing later.
Considering revenue-based financing? Fund your next milestone without touching your cap table
ECL funds B2B SaaS and AI companies with $500K+ ARR and a clear plan for the capital, with a Capital Consultant sizing the funding to the milestone you’re chasing and timing each tranche around when revenue lands.
Curious what this would cost for your business?
Run your numbers through the Cost of Capital Calculator, then talk to a Capital Consultant about whatever milestone you’re funding.
Frequently asked questions about revenue-based financing
1. Will revenue-based financing affect my next equity round?
Not in the way dilution does. Investors will see it in diligence as a repayment obligation, but it typically carries no warrants, so your cap table stays exactly where you left it. Use it to hit a revenue milestone first, and you can walk into your next raise negotiating from strength instead of need.
2. Can I repay revenue-based financing early?
Usually, yes, though the savings vary quite a bit by provider. Some charge the full fee no matter what, others discount it for paying early. ECL Flex offers prepayment savings of up to 30%, so it’s worth asking every provider exactly how early repayment changes the total cost.
3. What happens if my revenue drops during the repayment term?
On a variable model, payments fall automatically, though the term stretches out longer to compensate. On a fixed-term model, the payment stays the same regardless, so ask upfront what flexibility actually exists. ECL Flex, for instance, includes Skip-a-Pay and payment deferral options for exactly this situation.
4. Can I combine revenue-based financing with venture capital or venture debt?
Yes, and plenty of founders do exactly that, using non-dilutive capital to hit a milestone before the next equity round. Equity funds the vision, non-dilutive capital funds the execution. Some providers do require consent before you add other financing on top, so check for exclusivity clauses before you assume you’re free to mix and match.
5. How do I choose between revenue-based financing companies?
Look past the headline fee. Whether a provider calls itself revenue-based financing or revenue-based funding doesn’t matter nearly as much as the fine print. Check for warrants or personal guarantees, liens that limit other financing, what happens if revenue dips, and whether you can draw again later.

Founders who drive the future deserve capital that accelerates with them. Let’s make this the most efficient chapter of your story.